
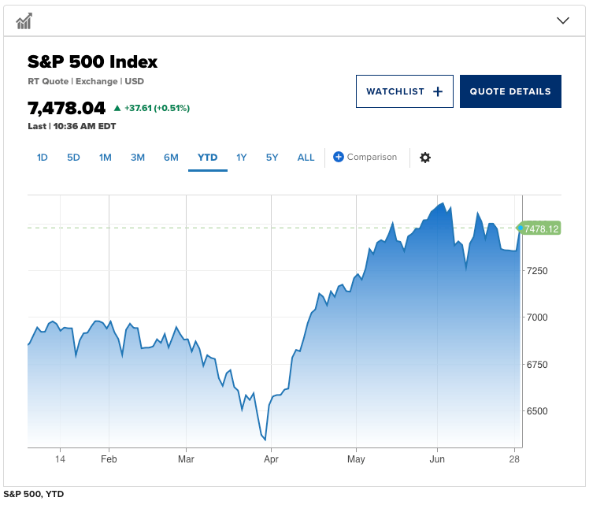
As the first half of the year draws to a close, there will be many headlines highlighting the strong market performance. The S&P 500 is up almost 9% YTD (below). The Dow Jones Industrial Average is hitting all-time highs. There are signs, however, that the market drivers are beginning to change which may affect overall returns going forward in the short term. The question that investors should be considering is whether the strong performance will continue into the back half of the year or whether it will take a time out?
Market Returns are Broadening
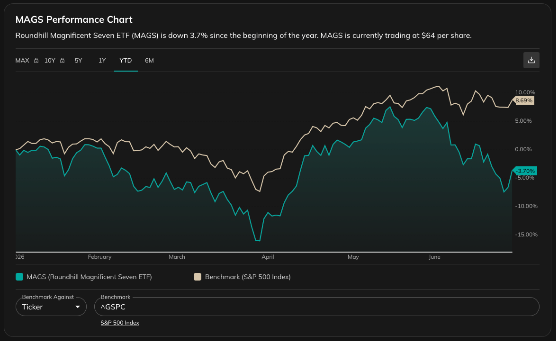
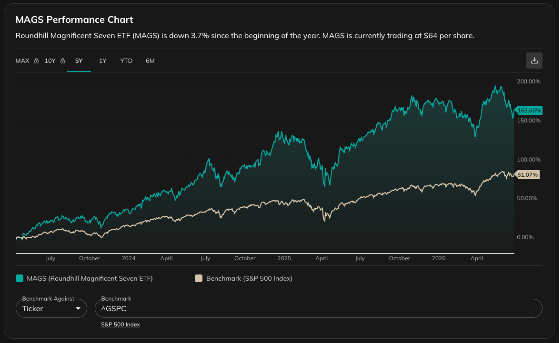
Investors have become used to the Magnificent 7 stocks driving the market to new highs. This year, however, we have seen a major broadening of the market. In fact, the Mag 7 stocks are lagging the market. Only Google is up 10%+ (11%) this year. While Tesla (-8%), Meta (-15%) and Microsoft (-24%) are down significantly. Recently, the S&P 500 has begun to outperform the Mag 7 stocks (below, first) unlike over the last 5 years (below, second).
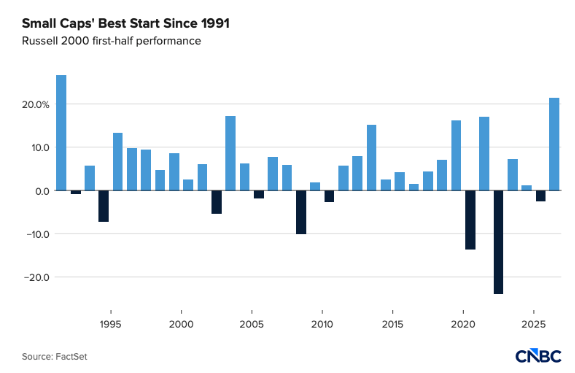
Given the high market weights of the Mag 7 on the S&P 500, it should come as no surprise that the equal weight S&P 500 ETF (RSP) has been outperforming the market cap weighted S&P 500 ETF (Spy). This outperformance extends to small caps as well. After a long period of underperforming their large cap peers, the Russell 2000 Index (a proxy for small caps, not micro caps) has had its best first half in 35 years (below). This highlights the broadening of market returns away from the megacap Mag 7 stocks and suggests that the market has taken more of a risk on flavour.
The AI Trade
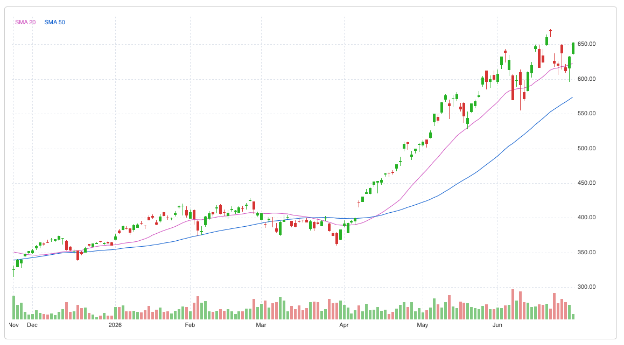
One of the concerns driving the underperformance of the Mag 7 has been the increasing concern over the levels of CapEx required to sustain a leadership position in AI. The issue investors are struggling with is that as these companies transition from asset light, cash generation machines to investment heavy, debt laden enterprises, can they generate sufficient returns on investment to justify the risks. Consequently, investors are increasingly turning to the “picks and shovels” investments – that is the equipment suppliers such as cooling, networking, electricity and especially semiconductors. Nvidia is no longer the only game in town. It is starting to feel the effects of large numbers and a near monopoly market share. As an example, the Van Eck Semiconductor ETF has risen over 80% this year while Nvidia has returned only 4.5% YTD.
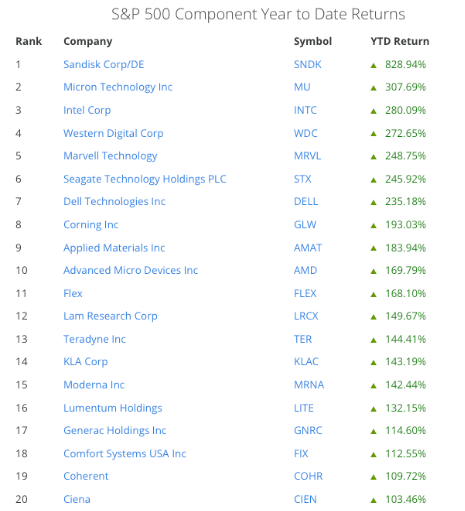
One need only look at the Top 20 performing stocks in the S&P 500 to see that the AI trade is alive but has changed its focus (below). Of the Top 20, only Moderna at #15 is not directly involved in the AI ecosystem. The list is dominated by Semis, semi equipment companies, and AI infrastructure providers. The thinking behind this trade is that while we don’t know who will win the AI race, we do know that all the major competitors will continue to spend at astronomical levels for the immediate future. The low risk trade has become those companies that supply into the ecosystem but are not exposed to the massive CapEx requirements. However, it should be noted that massive upswing of the leading companies in S&P 500 (by YTD returns) has meant that their multiples are exceedingly high compared to historical levels, leaving little room for error.
Investor Takeaway:
Markets are always looking for high return opportunities and compelling narratives. Thus, it is no surprise that rather than retreating in the face of increasing concerns about the AI trade, the market has changed focus to the suppliers (semis, infrastructure, electricity, etc.) from the providers (hyperscalers). One needs to be careful not to get caught in the late stages of a crowded trade as the risk reward balance shifts. While much of the money that has been exiting from the hyperscalers has moved into the AI enablers, there is still a case to be made for non-tech sectors to begin to rise. Diversification, as always, is prudent for more conservative investors. It is always important to maintain discipline when allocating portfolio resources.