
Quantitative Easing or QE was made famous during the Great Financial Crisis. It refers to a monetary policy whereby the Central Bank purchases bonds, shares or other assets in order to artificially stimulate economic activity. Typically, QE involves Central Banks buying bonds from other banks and financial institutions, (thereby lowering yields by creating excess demand for these bonds more than market forces alone could provide) and increasing money supply which in theory would allow banks to lend out into the economy to spur growth (below). It is used when rates fall very low (approaching zero), deflationary forces are rising and the economy is sluggish such as during the Great Financial Crisis. It is one of the most aggressive tools available to Central Bankers to stimulate growth and has only been used during times of crisis.
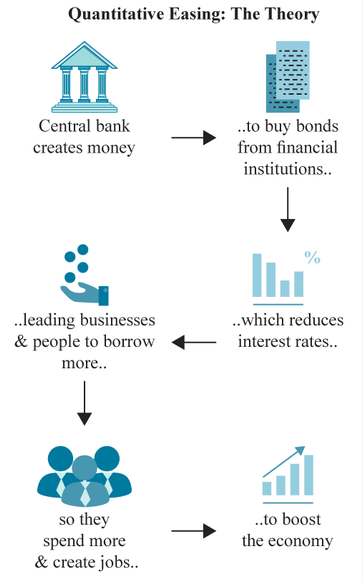
Treasury Secretary Scott Bessent recently announced the increase of market operations that were buying back long dated treasuries from $2B per operation to $4b+. This temporarily froze markets for 24 hours and rates declined before resuming their upward march. He followed this up with indications that the Treasury may use $1T of its balance sheet to support long-rates. Again, market reaction has been muted.
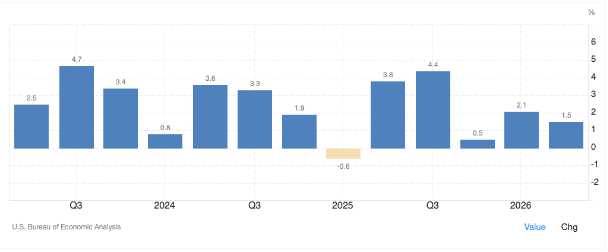
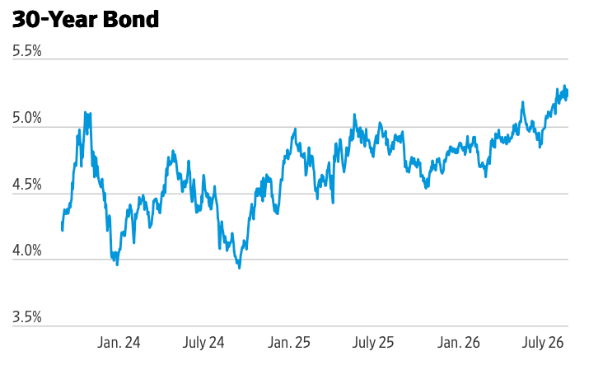
Given the US economy is growing (below, first), inflation is well above target and long-term rates have risen to well above 5% (below, second), why would the US even consider actions to lower rates?
First, the US is running deficits that are far above average. The projected deficit this year is expected to be in excess of $2T. Overall, the non-partisan Congressional Budget Office projects the US to borrow over $24T in the next 10 years. Shockingly, these figures are probably a large underestimation. They were built on several shaky assumptions:
- Tariffs will provide significant revenues (this assumption has proven hard to believe as the Supreme Court has severely limited Trump’s tariff powers).
- Recent tax breaks that were included in the One Big Beautiful Bill (i.e. no tax on tips) will expire in 2028 (Governments have continually demonstrated an unwillingness to claw back benefits once they have become ingrained).
- Social Security will slash benefits by at least 20% when the fund becomes insolvent around 2034 (this would be extremely unpopular with seniors).
None of this is to suggest that the US Government is in danger of going bankrupt, it is not. But if debts continue to rise faster than GDP than a reckoning is on the horizon. Debt payments account for more than half of the Federal deficit and are rising, especially on the back of higher interest rates. In its present condition, the US political system is incapable of taking the difficult actions required to address the problem – either raise taxes, reduce costs or both. They seem to be left with the only politically viable option which is to let inflation rise and devalue the debt through reduced purchasing power.
Second, the US is competing with corporates (primarily AI companies) for investor money. It is expected that AI companies may be issuing upwards of $2-3T of debt over the next few years. Most of the biggest corporate issuers have as good or better credit ratings than the US.
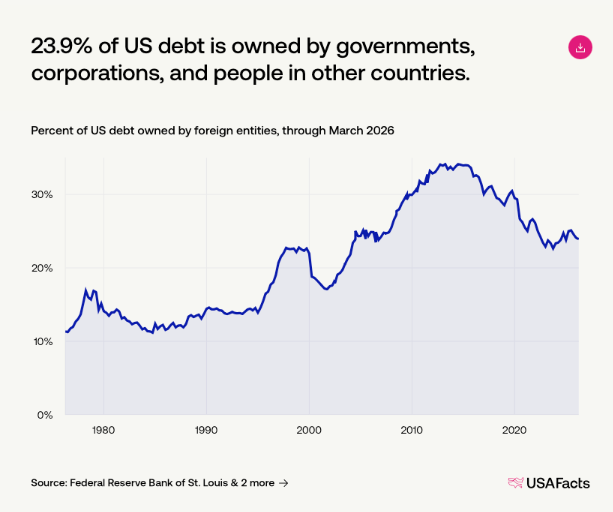
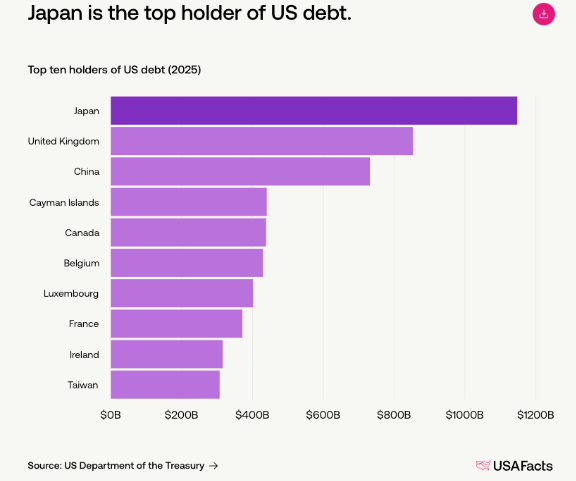
Third, the US is highly dependent on foreign buyers of debt. Almost one quarter of US debt is foreign owned. That amount is a sharp decrease from 10 years ago when it was over 33% (below, first). If foreign buyers continue to reduce purchases (most notably China has significantly cut their holdings), then this will cause strong upward pressure on rates. This makes the recent trade spat with Canada all the more perplexing as Canada has tripled its holdings of US Treasuries over the past 5 years to $460B (below, second), offsetting the decline in purchases by China. Essentially, Canada has been lending the US Government money at a significant clip, and they have responded by initiating punitive tariffs and a trade war.
Stanley Druckenmiller, a billionaire investor, recently wrote an Op-Ed piece in the Wall Street Journal making the case that the bond market will not respond well to government attempts at Yield Curve Control. He argues that US rates are not under pressure but are rather expressing the clearing prices reflective of an economy with high inflation (3-4%), low unemployment (4%) and governments deficits running at 6% of GDP. He estimates that at prevailing rates, interest expense reaches 4.5% of GDP by 2033 and 144% of all discretionary spending by 2043. He concludes that Governments attempting to defend prices against market fundamentals always lose.
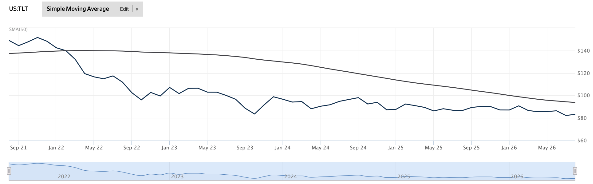
Rising rates have already been punishing long-term debt investors (below). If rates continue to rise, then the pain may continue. The TLT which is a basket of long dated bonds (20+ yrs) has dropped in half over the last 5 years far outweighing any dividends received.
Investor Takeaway:
One of the great risks that the US is taking with attempts at price controls on the bond market is increasing volatility. For decades, the US debt was seen as an island of stability for investors. Recently, they have been acting in response to short-term issues at the expense of long-term stability. They have been moving the bulk of borrowing to the short end of the yield curve in order to reduce payments. This increases interest rate risks for the government and reduces payment certainty as they have to continually roll over debt. If bond investors feel less confidence in the issuer, then they are likely to seek higher returns for their perceived risks. This will lead to higher yields and lower bond prices. Ill-conceived actions by the Government are likely to increase risk premia rather than lower rates in the long run. Investors interested in long-term bonds should consider skewing more heavily to high-grade corporate issuers rather than US Treasuries. It is likely that these bonds will exhibit less volatility over time.